Editorial intelligence only. Not legal, tax, or investment advice. Stamp duty rates and residency thresholds are current as of October 2026 and subject to legislative change. US citizens are subject to IRS worldwide income reporting obligations regardless of where they own property. Engage qualified Cayman Islands legal counsel before purchasing.
The Cayman Islands ranked first in the platform's 22-market Safe Haven Score — ahead of Singapore, Switzerland, and every other market the platform covers. The reasoning was straightforward: no market offers Americans a more complete combination of title security, tax absence, USD currency stability, banking infrastructure, and rule of law in a single jurisdiction. This buying guide bridges from that ranking to the actual process of purchasing property here as an American — including the one number that surprises almost every first-time buyer: the 7.5% stamp duty that is the only meaningful tax event in the entire transaction.
| Factor | Cayman Islands | Context |
|---|---|---|
| Foreign freehold | Full — no restrictions | Torrens title. Government-guaranteed |
| Stamp duty | 7.5% of purchase price | Paid at closing. Not financeable |
| Annual property tax | None | KYD 25/yr land register fee (~USD 30) |
| Income / capital gains tax | None | IRS worldwide income rules still apply to US citizens |
| Currency risk | Zero | KYD pegged 1.25 per USD since 1974 |
| Residency via property | USD 2.5M minimum | Residency Certificate for Persons of Independent Means |
| Total acquisition costs | ~9–10% all-in | 7.5% stamp duty + ~1.5–2% legal + ~2.5–3% agent |
Why the Cayman Islands Ranked #1: The Tax Structure Americans Need to Understand
Most Americans who research offshore property focus on the presence or absence of a property transfer tax, a capital gains tax, or an income tax on rental income. In the Cayman Islands, all three are absent — not reduced, not deferred, not available only under certain conditions, but structurally absent. The Cayman Islands has not enacted a personal income tax, a capital gains tax, a property tax, an inheritance or estate tax, or a wealth tax. This is not a tax holiday that expires, a treaty benefit that must be claimed, or a special economic zone arrangement. It is the baseline tax regime for all property in the Cayman Islands.
The tax event that does exist — stamp duty at 7.5% — is paid once at closing and never recurs. There is no annual property tax to budget against hold time. There is no capital gains tax on the proceeds when you sell. If you hold a Cayman property for 20 years and rent it the entire time, you pay no Cayman taxes on any of the rental income in any of those years. The cost basis for US tax purposes is the full purchase price, and US Schedule E rental income reporting applies to all US citizens regardless of where the rental property is located — but you are not paying Cayman taxes on top of that, and there is no Cayman withholding to navigate.
This structure is why the Cayman Islands scores 10 out of 10 on the platform's Tax Environment criterion — a perfect score no other market achieves. Dubai matches it on income and capital gains taxes but has a 4% DLD transfer fee. Cayman's transfer cost is higher (7.5% vs 4%) but its annual holding cost is zero vs Dubai's zero, making the two markets roughly comparable in total lifetime cost for long-hold investors, with Cayman's title system and legal infrastructure considered superior by most institutional buyers.
The CIREBA MLS: Why Cayman's Market Transparency Is Exceptional
One of the least-discussed advantages of buying in the Cayman Islands versus other Caribbean markets is the existence of CIREBA — the Cayman Islands Real Estate Brokers Association — which operates a functioning multiple listing service that covers the substantial majority of active listings in Grand Cayman. In most Caribbean markets (Barbados, St. Barts, St. Lucia, Turks and Caicos), there is no central MLS. Property is listed by individual brokers who share inventory inconsistently, prices are not publicly disclosed at sale, and buyers have no reliable way to determine what comparable properties have sold for. This creates information asymmetries that disadvantage buyers and make accurate valuation difficult.
In Cayman, the CIREBA MLS provides active listing data, days on market, and — for members — sold price history. This means a buyer working with a CIREBA member agent can access comparative sales data in a way that is simply not possible in most of the Caribbean. It also means that the Cayman market is more efficient and more liquid than peers: sellers price more accurately because comparable data exists, and buyers can make informed offers with the same data quality they would expect in a US market. For an American accustomed to the transparency of the US MLS system, Cayman offers a familiar and trustworthy process.
Grand Cayman Sub-Markets: Seven Mile Beach, South Sound, North Side, and East End
Seven Mile Beach is the most internationally recognised and most liquid sub-market in the Cayman Islands, and it commands the highest prices per square foot in the Caribbean. The beachfront corridor runs approximately 7 miles along the northwest coast of Grand Cayman from George Town north to Barkers National Park. Ownership is predominantly condominium — high-rise and mid-rise resort-style buildings with managed rental programmes — though beachfront villas exist at the top of the price range (USD 5M to USD 30M+). Liquidity is strong: Seven Mile Beach properties sell in weeks to months at the right price rather than the years-to-never horizon of some illiquid Caribbean sub-markets. Gross rental yields typically run 4% to 6% on managed condo programmes, with occupancy supported by Grand Cayman's consistent tourism volume.
South Sound is the preferred residential neighbourhood for Cayman's permanent and semi-permanent population — the financial services and legal professionals who constitute the working core of the jurisdiction. Properties here are predominantly single-family homes on canal-front or near-waterfront lots, with less hotel and resort infrastructure and a more genuinely residential character. Prices run USD 800,000 to USD 4 million. South Sound is where Americans planning extended stays or considering eventual residency tend to focus, because the neighbourhood functions as an actual community rather than a resort corridor.
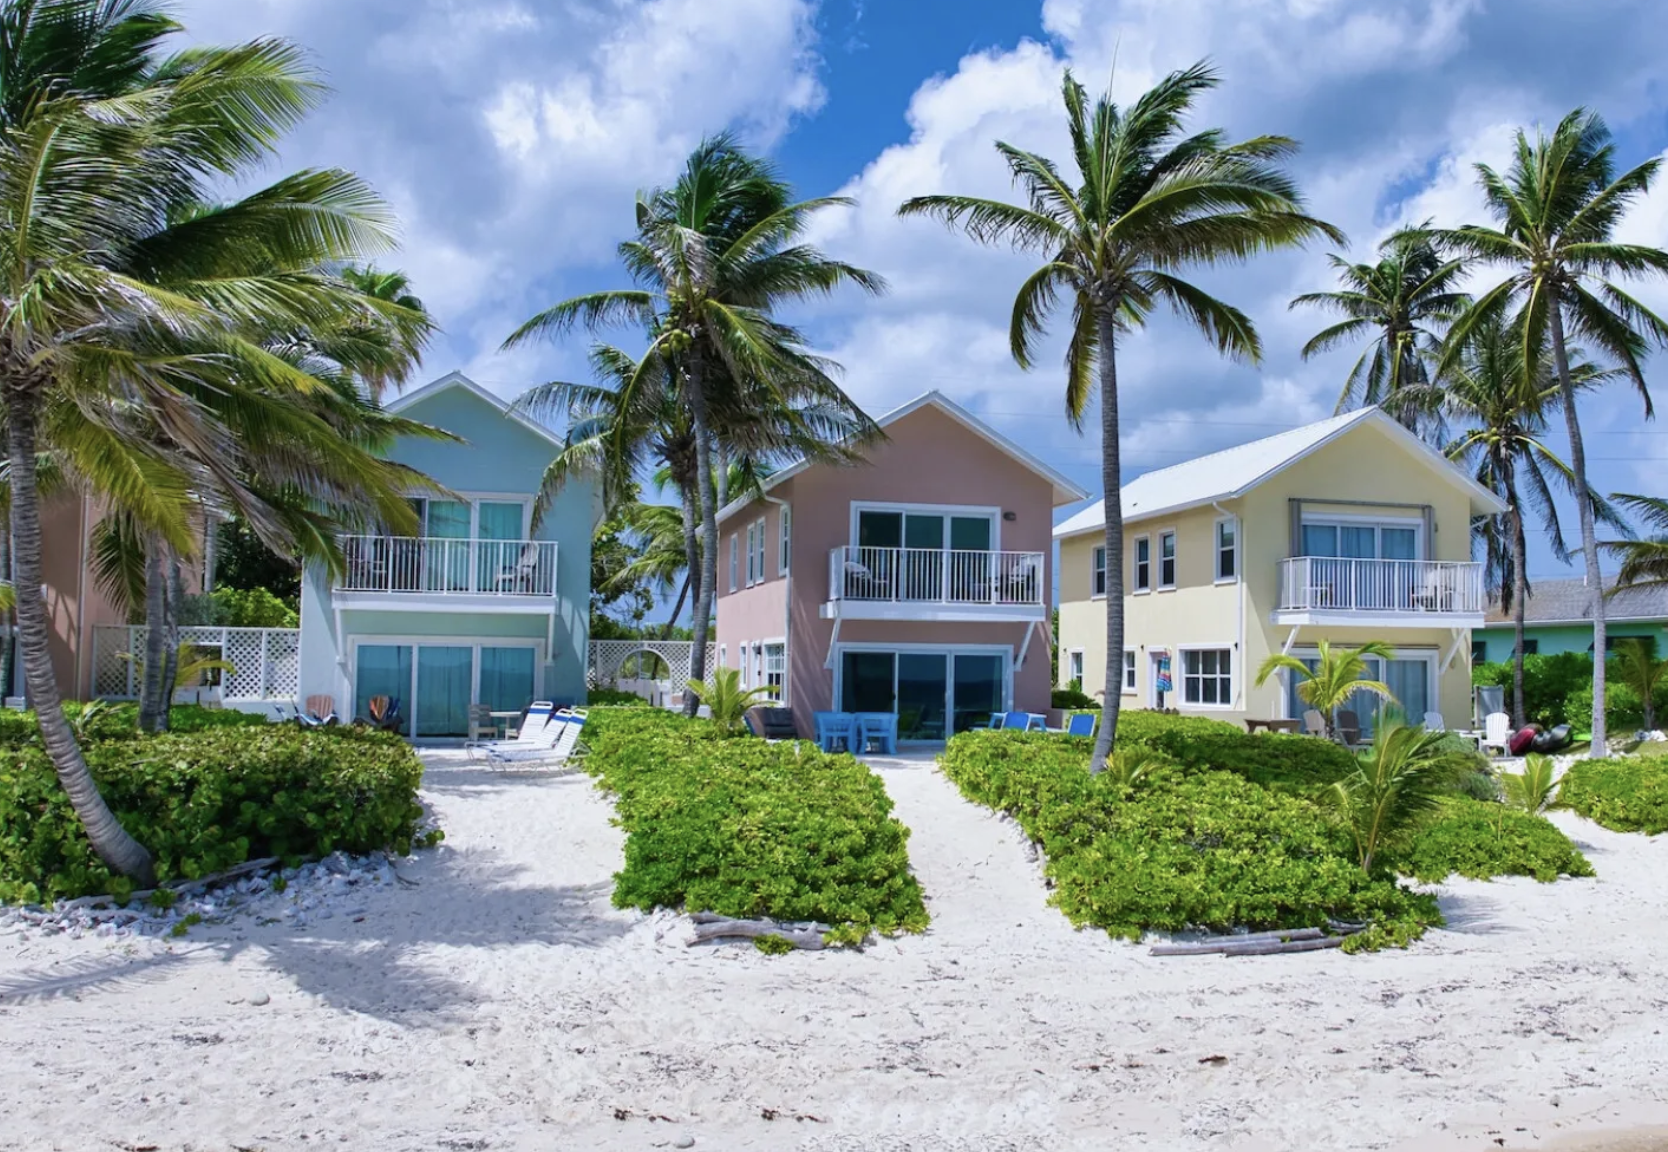
North Side and East End represent Grand Cayman's underdeveloped frontier. The drive from George Town is 25 to 40 minutes, which limits the rental appeal for short-term tourism but creates an opportunity for buyers seeking acreage, genuine privacy, and beachfront exposure at materially lower prices. A three-bedroom North Side home on or near the water — like the property in the photo above — can be acquired for under USD 1 million, a price point that is simply not available on Seven Mile Beach. East End draws serious divers (the dive sites off the east coast are among the best accessible from shore in the Caribbean) and buyers who prioritise the authentic Cayman environment over resort amenities.
The Transaction Process: Buying Property in the Cayman Islands as an American
The Cayman Islands transaction process is governed by Cayman Islands law (a common law system derived from English law) and administered through the Cayman Islands Land Registry. The process is straightforward and well-established for non-resident buyers.
Step 1: Engage a CIREBA member agent. A licensed Cayman Islands real estate broker is the starting point. CIREBA member agents have access to the MLS and are bound by the CIREBA Code of Ethics. Agent commission in Cayman is typically 5% to 6% of the purchase price, paid by the seller — buyer's broker compensation is included. The buyer pays no direct commission. Agents can represent both sides of a transaction (dual agency), which is legal in Cayman, though buyers benefit from engaging their own agent who is solely focused on their interests.
Step 2: Negotiate and execute a Sales Agreement. Once terms are agreed, a formal Sales Agreement is prepared — almost always by the buyer's Cayman Islands attorney, not the agent. A deposit of 10% of the purchase price is typically paid at this stage into an escrow held by the buyer's attorney. The Sales Agreement sets a closing date, typically 30 to 60 days later, and specifies the property's condition at handover.
Step 3: Title search and due diligence. Your Cayman attorney conducts a title search at the Cayman Islands Land Registry. Because Cayman uses the Torrens title system, the registered title is definitive — the registry search either confirms clean title or reveals encumbrances that must be resolved before closing. This is more reliable than the US abstract-of-title system and significantly more reliable than most Caribbean title systems. Environmental and planning searches are conducted in parallel.
Step 4: Close and pay stamp duty. At closing, the balance of the purchase price is paid. Stamp duty — 7.5% of the purchase price — is paid to the Cayman Islands government at or shortly after closing by the buyer's attorney. Failure to pay stamp duty triggers a penalty, so this is handled as a matter of course by Cayman attorneys on every transaction. Legal fees typically run 1% to 1.5% of the purchase price. The total closing cost for an American buyer is approximately 9% to 11% of the purchase price (7.5% stamp duty + 1–1.5% legal + agent commission already included in price). The title transfer is registered at the Land Registry, and the buyer is issued a new register of title.
The Cayman Islands ranked first in the platform's full 22-market Safe Haven Score. For the complete ranking methodology and how Cayman compares to Dubai, Singapore, the Bahamas, Turks and Caicos, and 17 other markets, see the full analysis.
See the 22-Market Ranking →Cayman Islands Residency for Americans: What Property Does and Doesn't Provide
Owning property in the Cayman Islands does not automatically provide residency. The pathway from property ownership to legal residency requires a specific investment structure and a separate government application. The primary route is the Residency Certificate for Persons of Independent Means — available to buyers who purchase a single developed property valued at KYD 2 million or more (approximately USD 2.5 million). The certificate grants the right to reside in the Cayman Islands indefinitely, is renewable annually, and does not include the right to work (a separate work permit is required for any employment income). The annual fee is USD 1,000. This is one of the cleaner residency-by-property pathways in the Caribbean — it is directly tied to a single property purchase rather than requiring a blind investment fund contribution — but the USD 2.5M threshold is meaningful.
For buyers who want legal residency in Cayman at a lower investment threshold, the Global Citizen Concierge Program (GCCP) offers a two-year renewable residence permit for remote workers and self-employed individuals earning at least USD 100,000 annually. The GCCP does not require property ownership — it is a visa category, not an investment programme — but many GCCP holders choose to purchase property once they establish their Cayman residency and confirm long-term intent. The GCCP is the practical entry point for Americans who want to spend extended time in Cayman before committing to the USD 2.5M investment threshold.
Americans who do not pursue formal residency benefit from the 180-day visa-free stay available to US citizens per entry, extendable once at the immigration department's discretion. In practice, Americans who own Cayman property and visit for 3 to 5 months per year typically operate without formal residency status, entering on the standard visitor permit and leaving before the period expires. This is a common pattern for second-home buyers who split time between the US and Cayman seasonally.
Hurricane Risk and Insurance: The Honest Assessment
Hurricane Ivan in September 2004 is the reference event in Cayman real estate. Ivan made direct landfall as a Category 5 storm and caused catastrophic damage across Grand Cayman — storm surge of 3 to 8 feet across the western and southern coasts, over 80% of structures damaged, and an estimated USD 3.4 billion in losses. The recovery took years. Ivan is why every American buying in Cayman should understand the hurricane risk framework before committing.
Post-Ivan, several things changed. Building codes were significantly upgraded. The Cayman Islands government established more rigorous construction standards for coastal and low-lying properties. The insurance market matured — windstorm and flood insurance is now standard, available, and required by Cayman mortgage lenders. Most Seven Mile Beach and canal-front properties are covered by comprehensive windstorm and flood policies. Premium rates reflect the risk: annual insurance costs on a USD 2 million Seven Mile Beach condo typically run USD 15,000 to USD 35,000 per year, which is a meaningful holding cost that buyers must factor into their total cost of ownership analysis.
The risk is real. Cayman sits in the active Atlantic hurricane belt. The question is not whether Cayman has hurricane exposure but whether the combination of improved construction standards, available insurance, strong legal infrastructure, and complete tax absence justifies the risk premium — a calculation each buyer must make based on their own risk tolerance and time horizon. The platform's position: Cayman's structural advantages are significant enough to justify the risk for buyers who insure appropriately, understand the Ivan precedent, and are buying with a multi-decade time horizon.
Mortgages and Financing for American Buyers
Cayman's banking sector is among the most sophisticated in the Caribbean. The major retail banks — Butterfield Bank, Cayman National Bank, RBC Royal Bank, and CIBC FirstCaribbean — all lend to non-resident foreign buyers on Cayman property, which is relatively unusual in the Caribbean context. Most other island markets (Turks and Caicos, Anguilla, St. Barts) offer very limited non-resident mortgage access, pushing buyers toward all-cash purchases.
For American buyers, Cayman bank mortgages typically offer: 60% to 70% loan-to-value (requiring 30% to 40% cash deposit plus the 7.5% stamp duty); interest rates approximately 1% to 2.5% above US prime rate; 15 to 25-year terms; and USD-denominated loans. Underwriting requires US income documentation, US federal tax returns for 2 to 3 years, a credit report, and a Cayman property appraisal. The process is more similar to a US mortgage application than what buyers encounter in most European or Asian markets. However, the combination of stamp duty (7.5%, cash only) and minimum deposit (30%+) means American buyers should expect to have 37% to 40% of the purchase price available in cash at closing in addition to any mortgage financing.
Evaluating the Cayman Islands alongside other Caribbean or global markets? Peter Tumbas provides cross-market context for American buyers considering international property. Initial consultations are complimentary.
Peter Tumbas, REALTOR® · Berkshire Hathaway HomeServices New England Properties · CT License RES.0836133
Peter Tumbas advises American buyers evaluating international property markets across the Caribbean, Europe, the Gulf, and Southeast Asia. He founded the Safe Havens for Americans platform to provide independent, non-promotional intelligence on the markets and processes Americans encounter when purchasing property abroad.