Editorial intelligence only. Not legal, tax, immigration, or financial advice. IRS worldwide income reporting obligations apply to all US citizens regardless of where they own property or reside. All prices in USD are approximations based on AED/USD rates as of October 2026 (AED 1 = approximately USD 0.272). Engage qualified legal, tax, and real estate specialists before making any purchasing decision.
Dubai is the most searched international property market among high-net-worth Americans on this platform, and for defensible reasons. The combination of zero personal income tax, zero capital gains tax, AED pegged to the US dollar since 1997, and a 10-year Golden Visa available from approximately USD 545,000 is unique among global gateway cities. The process of actually buying is more straightforward than most Americans expect. This guide covers every step — freehold zone selection, the DLD transaction process, off-plan vs resale trade-offs, mortgage access for Americans, the Golden Visa pathway, and the IRS obligations that apply regardless of Dubai's zero-tax environment. For the full market intelligence picture on Dubai, including neighborhood-by-neighborhood analysis and developer due diligence frameworks, visit dubaiforamericans.com.
| Factor | Dubai | Key Detail |
|---|---|---|
| Foreign ownership | Full freehold in 65+ zones | No surcharge, no approval required |
| Transfer fee | 4% DLD fee | On the higher of contract price or DLD assessed value |
| Income / capital gains tax | Zero | UAE has no personal income or capital gains tax |
| Currency risk | None | AED pegged to USD at 3.6725 since 1997 |
| Golden Visa threshold | AED 2M (~USD 545K) | 10-year renewable residency, no min. stay |
| Remote purchase | Yes | Power of Attorney notarised and apostilled in the US |
The Freehold Zone System: Where Americans Can Own in Dubai
Dubai's Land Department divided the emirate into freehold and non-freehold zones in 2002, opening designated areas to non-UAE nationals for the first time. That list has expanded steadily — there are now more than 65 designated freehold zones, covering virtually every major residential and mixed-use development in the city. What this means practically: Americans have enormous geographic choice when buying in Dubai.
The most established freehold zones for international buyers include: Dubai Marina, a waterfront high-rise district with strong rental demand from finance and technology professionals; Downtown Dubai, anchored by the Burj Khalifa and Dubai Mall, the flagship address in the city; Palm Jumeirah, the artificial island with branded hotels and ultra-luxury villas; Business Bay, the commercial and residential core on the Dubai Water Canal; Dubai Hills Estate, the master-planned villa and townhouse community around an 18-hole golf course; Arabian Ranches, the original premium villa community with a mature community feel; and Jumeirah Village Circle (JVC), the most affordable freehold entry point in a connected location.
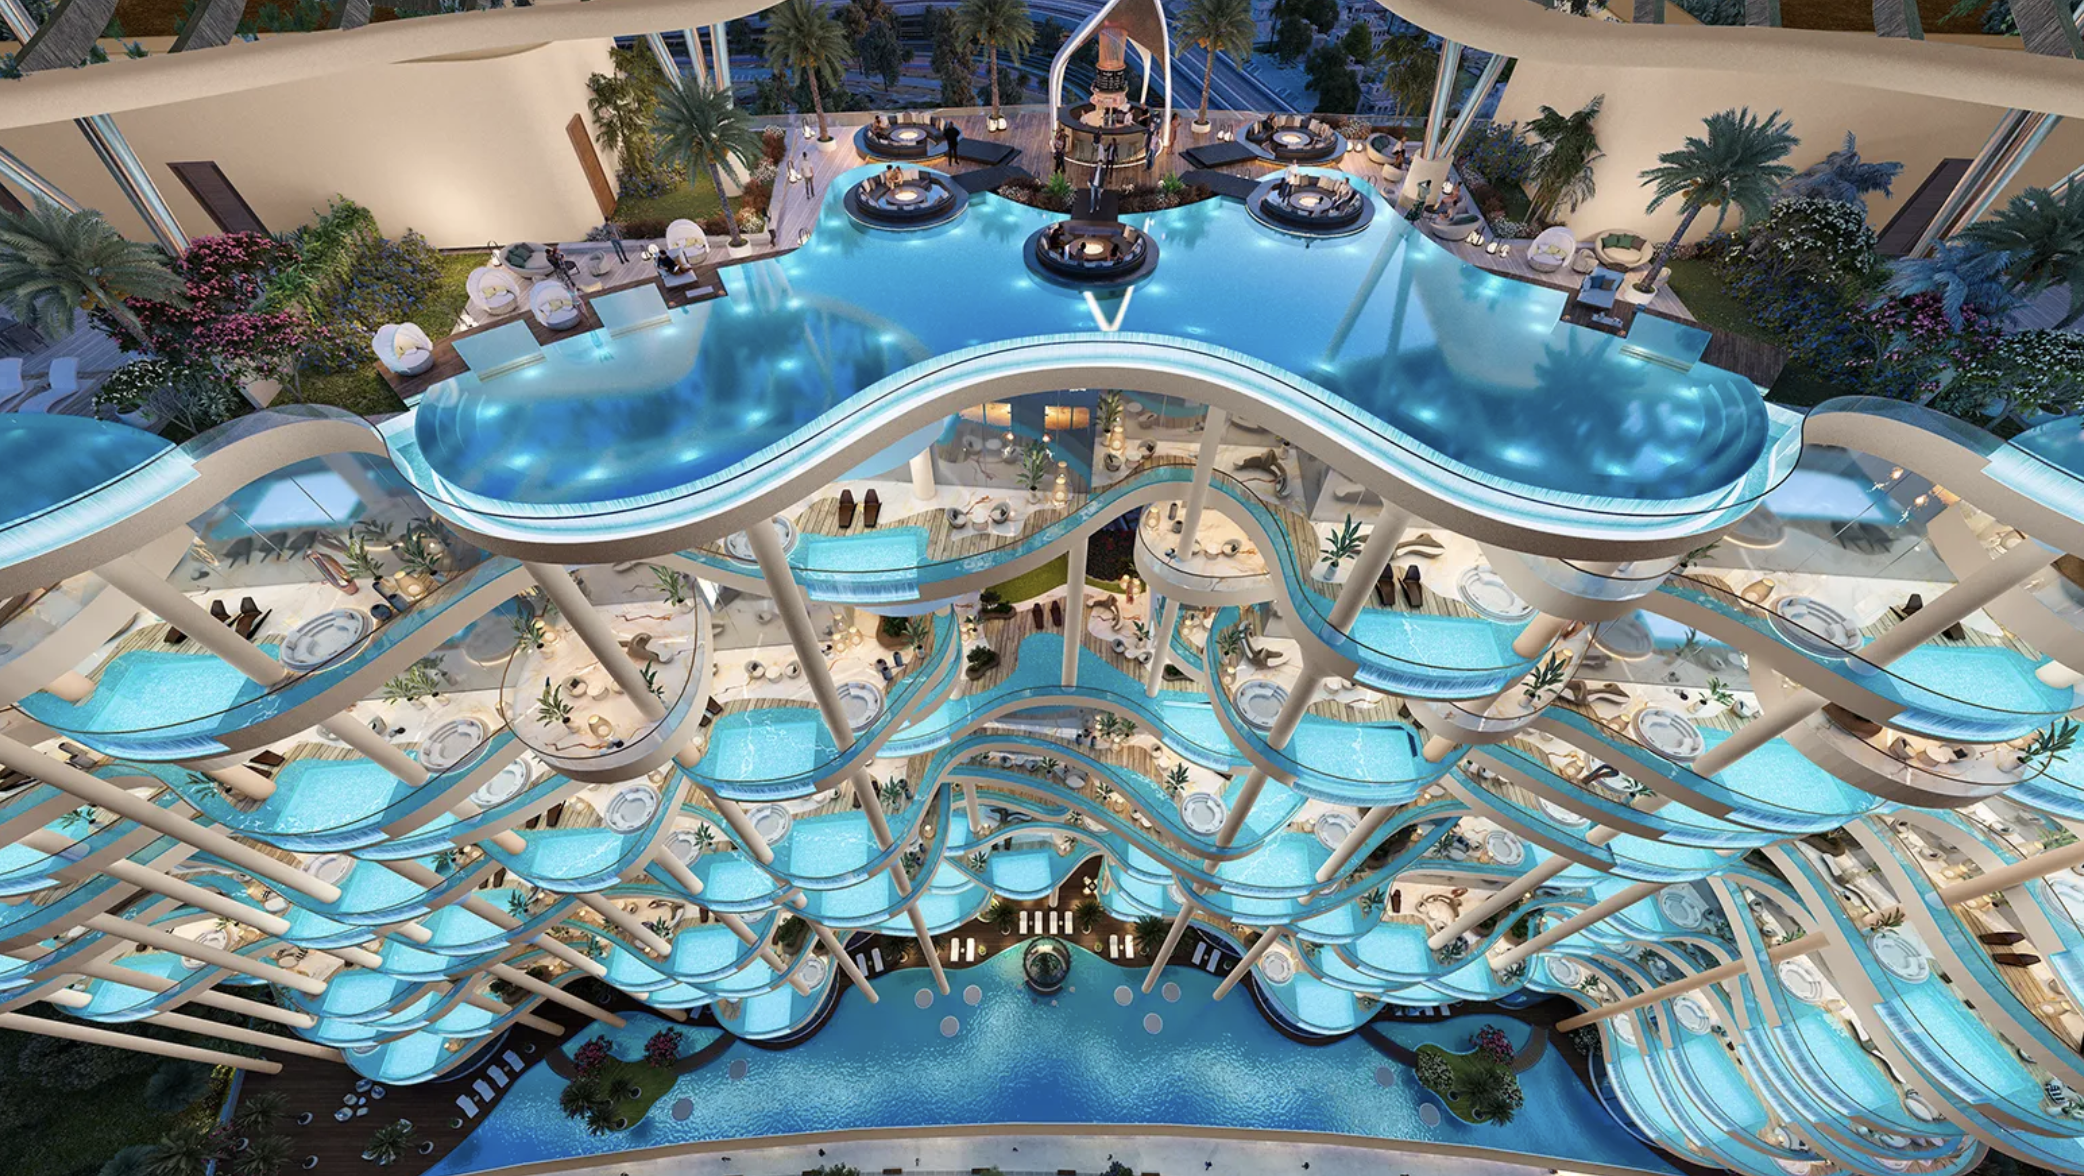
Newer freehold zones expanding the Dubai market's inventory in 2025 and 2026 include Dubai Creek Harbour (the Emaar waterfront development surrounding the planned Dubai Creek Tower), Meydan City, Sobha Hartland, and Mohammed Bin Rashid City. The Couture by Cavalli development pictured above is located on the Dubai Water Canal in Business Bay — classified as freehold. For a neighbourhood-by-neighbourhood breakdown with current price-per-square-foot data, visit dubaiforamericans.com.
The DLD Transaction Process: Step by Step
The Dubai Land Department (DLD) administers all property registrations in the emirate. The resale transaction follows a well-established sequence that American buyers find more transparent and faster than most US states. Here is the complete process:
Step 1: Agree the price and sign the MOU. Once buyer and seller agree on price verbally, a Memorandum of Understanding (MOU, also called Form F) is drafted — typically by the agent. Both parties sign, and the buyer pays a 10% holding deposit into the agent's escrow account or directly to the seller (the method varies by agency). This secures the property and sets the closing timeline, typically 30 to 45 days.
Step 2: Obtain the No Objection Certificate (NOC). The seller applies to the developer for a No Objection Certificate confirming no outstanding service charges or dues on the property. This takes 5 to 10 business days and costs AED 500 to AED 5,000 depending on the developer. Without the NOC, the DLD will not process the transfer.
Step 3: Arrange funds clearance. The buyer's funds must be available in UAE dirhams before the transfer appointment. Americans typically arrange an international wire in USD to a UAE account, then convert to AED. Allow 3 to 5 business days for correspondent banking. The DLD requires a manager's cheque or bank draft in AED for the 4% DLD fee and registration trustee fee — not a wire or personal cheque at the transfer appointment itself.
Step 4: Attend the DLD trustee office for transfer. Dubai has a network of DLD-registered trustee offices where transfers are executed. Both buyer and seller (or their attorneys-in-fact) attend in person. The process takes approximately 30 to 60 minutes. The DLD digital title deed — the eTitleDeed — is issued same day and emailed to the buyer. There is no delay between transaction execution and title registration in Dubai, unlike the title insurance and recording lag common in US states.
Step 5: Register for services and apply for Golden Visa if applicable. After receiving the eTitleDeed, buyers register utilities with DEWA (Dubai Electricity and Water Authority), engage a property management company if renting out, and initiate the Golden Visa application through the GDRFA if the property qualifies. The Golden Visa application typically takes 3 to 4 weeks and requires the eTitleDeed, passport, photos, medical fitness certificate, and Emirates ID application.
Can Americans buy remotely? Yes. A Power of Attorney (POA) notarised in the US and apostilled under the Hague Convention allows a local representative in Dubai to execute the MOU, attend the DLD transfer, and complete all administrative steps on the buyer's behalf. Many American buyers complete their first Dubai purchase without visiting. The POA must specifically enumerate the powers being granted — a general POA is typically not accepted by the DLD trustee offices.
Off-Plan in Dubai: The Opportunity and the Risks
Dubai's off-plan market is one of the most active globally. Developers — led by Emaar, DAMAC, Sobha, Nakheel, and Aldar — launch new projects multiple times per year, often selling out in hours at launch prices. For Americans, off-plan offers genuine advantages and specific risks worth understanding.
The off-plan advantage is price and payment structure. Launch prices are typically 10% to 20% below the comparable completed price for the same location and specification. Payment plans spread the purchase across construction milestones: a common structure is 20% on signing, 10% every six months during construction, and 40% on handover. This allows a buyer to control an AED 2 million property with AED 400,000 initially, while the remaining AED 1.6 million funds over 18 to 36 months. Some developers offer post-handover payment plans extending 2 to 3 years after completion. Developer commissions to buyer's agents are standard — the buyer pays nothing to their agent on most off-plan purchases.
The off-plan risks are real and must be understood. Construction delays are common — a project quoted for 2026 delivery may not complete until 2028. Developer insolvency, while protected against by RERA escrow requirements, has historically resulted in project cancellations in the 2008 to 2011 downturn. RERA requires developers to hold buyer funds in escrow accounts and release them only at verified construction milestones — this is a meaningful protection absent in many other markets, but it does not eliminate delay risk. Off-plan properties cannot be used or rented until handover, eliminating near-term income. Crucially for Golden Visa purposes, off-plan properties are not eligible for the residency application until the Oqood (provisional registration with the DLD) has been issued — typically when construction reaches a specified completion percentage.
Developer due diligence matters. Before committing to any off-plan project, verify the developer holds a valid RERA registration, confirm the project has an approved escrow account registered with RERA, review the construction track record of the specific developer (not the marketing agent's claims), and review the unit floor plan and specifications with an independent architect if commissioning a high-value unit. For a current list of RERA-registered developers and projects, visit the Dubai REST portal. For developer track record analysis specific to American buyers, dubaiforamericans.com maintains updated assessments.
The Golden Visa: 10-Year UAE Residency Through Property
The UAE Golden Visa introduced in 2019 and expanded significantly in 2022 is the most compelling residency-by-investment pathway available to Americans in the Gulf. The property route requires a minimum AED 2,000,000 (approximately USD 545,000) in freehold property within the UAE — Dubai is by far the most popular jurisdiction for property-based applications, but Abu Dhabi and Ras Al Khaimah freehold also qualify.
The Golden Visa grants 10-year renewable UAE residency to the property owner, their spouse, and all children under 18. Adult children over 18 who are students can be included if enrolled in UAE educational institutions. Parents of the investor can be sponsored under a separate long-term parent visa. The investor can also sponsor domestic workers.
The key operational reality for Americans: there is no minimum annual stay requirement for the Golden Visa. An American can buy qualifying property, obtain the Golden Visa, and spend zero time in the UAE without the visa expiring. This distinguishes Dubai's programme from Portugal's NHR (which requires 183 days for tax benefit), Costa Rica's Investor Residency (which requires periodic renewal trips), and most European programmes. The Golden Visa renews on the continued ownership of the qualifying property — sell the property and the visa lapses at renewal.
What the Golden Visa provides: legal UAE residency that allows banking access, driving licence conversion, Emirates ID, school enrolment for children, and the ability to sponsor staff. What it does not provide: UAE citizenship (not currently available to investors outside exceptional circumstances), the right to vote, or any automatic tax benefit for US citizens (who remain IRS-obligated on worldwide income regardless of UAE residency). Some Americans pursue the Golden Visa as a genuine residency base — living in Dubai for a material portion of the year to access the lifestyle and business ecosystem. Others treat it as a strategic optionality tool — a legal right to base in a zero-tax, dollar-pegged city that costs only the property purchase to maintain.
For neighbourhood-by-neighbourhood pricing, developer track records, Golden Visa application logistics, and off-plan market analysis updated monthly, visit the dedicated Dubai resource for American buyers.
Visit DubaiForAmericans.com →Mortgages in Dubai: Can Americans Get Financing?
Americans can obtain mortgages in Dubai, but the landscape differs materially from US lending. UAE banks offer mortgages to non-resident foreigners, including Americans, on both completed freehold properties and selected off-plan projects. The practical constraints:
Loan-to-Value (LTV) ratios. The UAE Central Bank caps non-resident LTV at 60% on properties below AED 5 million and 55% on properties above AED 5 million. This means an American buying a AED 2 million apartment needs at least AED 800,000 (40%) in cash equity at closing. US banks do not lend against UAE property.
Interest rates and terms. UAE mortgage rates in 2026 are typically EIBOR-linked (Emirates Interbank Offered Rate) plus a margin of 1.25% to 1.75%, resulting in effective rates of 5.5% to 7% depending on the bank and profile. Fixed-rate periods of 3 to 5 years are available on some products. Mortgage terms run up to 25 years for freehold property but are usually capped at the retirement age of 65 minus the applicant's current age. A 50-year-old American borrower would typically be limited to a 15-year term.
Documentation requirements for Americans. UAE banks require: valid US passport; last 3 to 6 months of US bank statements; last 2 years of US tax returns or CPA letter confirming income; evidence of source of funds; and a UAE credit check (which will show no history for first-time applicants — banks accommodate this with higher documentation standards). Self-employed Americans face more scrutiny than salaried applicants.
Strategic note: Many Americans buying in Dubai for Golden Visa qualification purchase cash and avoid the mortgage complexity entirely. The Golden Visa requires the AED 2 million to be either fully paid or supported by at least AED 2 million in equity if a mortgage exists. Mortgaging down to 60% LTV on a AED 2 million property would leave only AED 800,000 in equity — below the Golden Visa threshold. To combine a mortgage with Golden Visa eligibility, the property value needs to be AED 5 million or higher with a 60% LTV, leaving AED 2 million in equity, or the buyer must commit to a lower LTV.
Rental Yields and the Dubai Investment Case
Dubai generates some of the strongest gross rental yields of any major global gateway city. Average gross yields by zone in 2026: Dubai Marina and JBR — 5.5% to 7%. Business Bay — 5.5% to 7%. JVC and JVT — 6% to 8%. Downtown Dubai — 4.5% to 6%. Palm Jumeirah — 4% to 5.5% (lower yield, higher capital appreciation potential). Dubai Hills — 4.5% to 5.5% on villas. Ultra-luxury branded residences like Couture by Cavalli typically yield 3.5% to 5% gross — the premium is paid for in price appreciation potential and the lifestyle proposition, not the income yield.
Dubai's rental market has specific structural features that affect income reliability. Short-term rental via Airbnb and DTCM-licensed operators is legal and common in Dubai — average nightly rates in Marina and Downtown range AED 500 to AED 1,800 for a one-bedroom. Annual tenancy via the Ejari system provides more stable income with legal tenant protections enforced through the RDSC (Rental Dispute Settlement Centre). Many American owners use annual tenancy for the first year to establish income, then evaluate short-term rental management if yield improvement is the objective.
Net yields after management fees (5% to 8% of gross rent for annual, 15% to 20% for short-term), service charges (AED 15 to AED 50 per sq ft per year depending on development), and US tax on rental income typically run 3% to 5.5%. This compares favourably with London (1% to 3% net), Sydney (2% to 3.5% net), and Paris (2% to 3% net) for dollar-based investors. For detailed rental market data and operator comparisons, dubaiforamericans.com publishes quarterly yield analysis.
US Tax Obligations: What the IRS Requires Regardless of Dubai's Zero-Tax Environment
This is the section most Dubai real estate marketing omits, and it is critical for American buyers. The United States taxes its citizens on worldwide income regardless of where they live or where income is earned. Dubai's zero income tax and zero capital gains tax apply to Dubai residents — they do not exempt Americans from IRS obligations.
Rental income. Rental income from Dubai property is fully taxable in the US. The income is reported on Schedule E (Form 1040) as foreign rental income. Americans can deduct mortgage interest (if applicable), property management fees, repairs, and a portion of service charges. Depreciation on the property (foreign residential real estate is depreciated over 40 years under US tax rules, versus 27.5 years for US residential property) can offset rental income. The net rental income is taxed at ordinary income rates. There is no US-UAE tax treaty to provide credit or relief.
Capital gains on sale. Profit on the sale of Dubai property is a capital gain taxable in the US. Long-term capital gains rates (0%, 15%, or 20% depending on income) apply to property held more than one year. The Section 121 primary residence exclusion ($250,000 per person, $500,000 for married couples) applies only to a US person's primary residence — an investment property in Dubai does not qualify regardless of how much time is spent there.
FBAR and FATCA. Americans with Dubai bank accounts (used for rental management, for example) exceeding USD 10,000 at any point during the year must file FinCEN Form 114 (FBAR). Americans with foreign financial accounts and assets above certain thresholds must report under FATCA (Form 8938). A property itself is not a foreign financial account and is not directly reportable on the FBAR, but the rental management account or any UAE brokerage account holding sales proceeds is.
The practical planning implication: Dubai's zero-tax status benefits UAE residents and non-US citizens living in Dubai, not Americans earning passive income from Dubai property while residing in the US. The tax advantage for Americans is indirect — no additional UAE tax layer on top of US obligations, which avoids the double-taxation complexity present in France, Germany, Spain, and most European markets. Consult a CPA with international tax experience before closing.
Branded and Ultra-Luxury Residences: The Couture by Cavalli Market
The segment attracting the most American buyer interest in Dubai in 2025 and 2026 is branded ultra-luxury residential — projects where fashion, hospitality, and automotive brands license their names to residential developments. Couture by Cavalli (pictured above) on the Dubai Water Canal is one of the most prominent current launches, developed by DAMAC in collaboration with Roberto Cavalli. The development offers waterfront residences with the full Cavalli interior design language — marble, gold detailing, and bespoke furniture packages — in a prime Business Bay location with direct canal frontage.
Other active branded residential launches in Dubai in 2026 include: Bugatti Residences by Binghatti (Business Bay); Mercedes-Benz Places by Binghatti (Downtown Dubai); Baccarat Hotel and Residences (Downtown); and multiple Four Seasons, Six Senses, and Aman-adjacent residential projects across Palm Jumeirah and Business Bay. Pricing in this segment runs AED 8,000 to AED 25,000 per square foot — USD 2.2 million to USD 6.8 million for a typical 1,000 sq ft unit.
The investment thesis for branded residences is distinct from standard Dubai property. Gross yields are lower (3% to 5%), but resale premiums above the broader market are historically documented in established branded projects globally. The buyer profile is typically a high-net-worth individual purchasing as a lifestyle asset with wealth preservation rather than income maximisation as the primary objective. Due diligence should include review of the brand licensing agreement (some brands licence only interiors with no ongoing hotel management commitment), the developer's completion track record, and the HOA governance structure post-completion.
Working with an Agent: Dubai Market Conventions Americans Should Know
Dubai's real estate agency market is large, loosely regulated in practice despite RERA licensing requirements, and characterised by high agent turnover. Americans approaching the Dubai market for the first time encounter conventions that differ from US norms:
Dual agency is standard. In Dubai, the same agent frequently represents both buyer and seller. This is legally permitted and disclosed in the MOU. Americans accustomed to buyer agency representation should be aware that the agent presenting a property often has a contractual duty to the seller. Independent buyer's advocates who charge a separate fee to represent buyer interests exclusively are available but not the norm.
Commissions are paid by the buyer on resale. Unlike most US markets where the seller pays total commission, Dubai resale convention is that the buyer pays 2% commission to the buyer's agent and the seller pays 2% to the seller's agent — each side typically bears their own agent cost. On developer off-plan, the developer pays the agent's commission entirely.
RERA registration is the minimum credential check. All practising agents in Dubai are required to hold a RERA Broker Card. Verify your agent's RERA registration number on the Dubai REST app before proceeding. Unregistered agents are common and present legal risks for transaction documentation.
Referral relationships matter. Americans buying in Dubai often benefit from a US-based real estate professional with established Dubai relationships who can provide an independent layer of due diligence and coordinate with a trusted on-the-ground Dubai agent. The dubaiforamericans.com network maintains vetted agent relationships across the primary Dubai freehold zones.
Ready to move from intelligence to action on Dubai property? Peter Tumbas works with American buyers navigating the Dubai market, coordinating the on-the-ground relationships and due diligence you need before committing capital. Initial consultations are complimentary.
Peter Tumbas, REALTOR® · Berkshire Hathaway HomeServices New England Properties · CT License RES.0836133
Peter Tumbas advises American buyers evaluating international property markets across Europe, the Gulf, Southeast Asia, and the Caribbean. He founded the Safe Havens for Americans platform to provide independent, non-promotional intelligence on the markets and processes Americans encounter when purchasing property abroad. He is based in Connecticut and licensed in multiple US states.